For Canadians saving a first down payment, the first-home account blends tax-deductible contributions with tax-free qualifying withdrawals, helping buyers build funds faster.
This account combines retirement-account-style deductions with tax-free qualifying withdrawals, but money taken for anything other than a home purchase becomes taxable income.
Key limits: $8K yearly, $40K lifetime, up to 15 yr of contributions, and carried-forward room capped at $8K, allowing $16K in one year.
If buying plans change, unused funds can transfer to a retirement account tax-deferred, while moving money into a tax-free account requires a taxable withdrawal.
For first-home savings, prioritizing the first-home account can accelerate down payment growth and tax savings; after purchase, the tax-free account supports broader long-term goals.
-
FHSA Beats TFSA for Home Savings
-
Housing Slowdown May Spark Future Building Opportunities
Canada may face a housing shortage if construction slows, as demand could outpace supply when the market recovers. Affordability improvements may be short-lived, and there is a mismatch in housing types. Modernizing building methods and maintaining construction capacity are essential for long-term needs.
Continue to full article -
Small-Scale Infill Expands Canada’s Housing Supply
Small-scale infill had been taking a larger role in housing starts, even though larger developments still delivered most new construction across established neighborhoods.
Zoning changes allowing more homes on existing lots suggested supply could shift upward, especially where infill rules became more permissive within established neighborhoods.
The broader housing pattern showed more building on previously developed land, with new construction becoming denser and ground-oriented homes representing a smaller share.
Recent policy changes helped enable more missing middle housing, but project momentum still depended on fees, approval timelines, building rules, and financing.
Small-scale infill emerged as an important source of ground-oriented homes, while its longer-term growth still hinged on whether projects remained financially viable. -
Happy Halloween
Halloween falls on October 31 because the ancient Gaelic festival of Samhain, considered the earliest known root of Halloween, occurred on this day.
In the eighth century, Pope Gregory III designated November 1 as a time to praise all saints.
Soon, All Saints' Day incorporated some traditions of Samhain and the evening before was known as All Hallows Eve, and later Halloween.
Over time, Halloween evolved into a day of activities like trick-or-treating, carving jack-o-lanterns, festive gatherings, donning costumes and eating treats.
Today’s the day to eat candies and sweets to your heart’s content! Happy Halloween! -
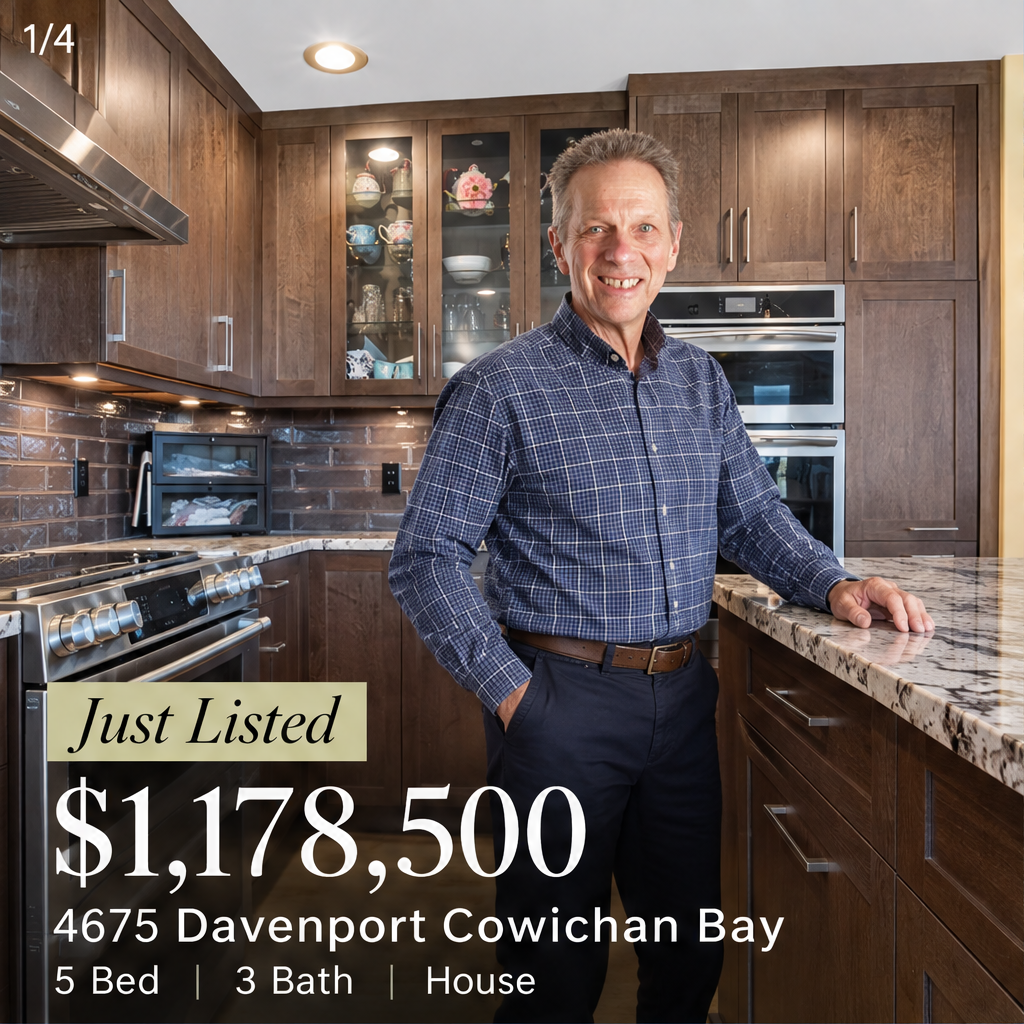
4675 Davenport Cowichan Bay, British Columbia V0R1N1
Ocean Views in Cowichan Bay — 4675 Davenport Road – Enjoy excellent ocean views from this main-level entry home, perfectly situated in the heart of Cowichan Bay. The top floor has been completely upgraded from top to bottom — new flooring, Fireplace, kitchen – with 3 ovens & an induction range, and bathrooms — offering a fresh, move-in-ready living space with those stunning water views to enjoy every day. 3 bedrooms on this floor and the ensuite is amazing! The lower floor has been used as an in-law suite, with two more bedrooms kitchen and bathroom offering excellent flexibility for extended family, guests, or additional income potential. The bonus is all the additional storage that is available! With breathtaking ocean views, quality upgrades throughout, and versatile living space, 4675 Davenport Road is a standout opportunity in one of Cowichan Bay's most desirable settings. (id:26452)
Continue to full article -
Canada Buyers Gain More Choice in 2026
Stable borrowing costs and firm housing costs are giving active buyers a clearer planning window, with accessible entry points emerging in several markets.
After years of unpredictable inventory, rates, remote work, trade policy, and inflation, softer price growth points toward a more normal 2026 market.
The central bank suggested its overnight lending rate may hold near 2% for much, if not all, of 2026, supporting buyer confidence.
Balanced or buyer-favoured regions give shoppers more time to compare options, focus on fit, and avoid rushed decisions under pressure in 2026.
Fredericton led the national 2026 ranking again, combining East Coast affordability, equity-building potential, market stability, and lifestyle appeal for buyers seeking value. -
Canada’s First-Time Home Buyer Rebate
Five application types determine who files, what forms are needed, and the deadline for a new, substantially renovated, or co-op home rebate claim.
For builder-filed claims, buyers who agree to a rebate credit must sign Form GST190, while the builder submits documents, including adjustments and purchase agreement copies.
If builder does not credit the rebate, file online or by mail, adding Ontario's schedule if applicable, within 2 yr of transfer or possession.
Co-op share buyers always file their own claim, and some could apply later for the first-time buyer rebate if filings came before March 12, 2026.
If only the new housing rebate was credited, buyers could separately claim the first-time buyer rebate; modular, mobile, and floating homes require separate guidance. -
When Buying a Home Makes Financial Sense
A recent poll found 64% of Canadians said no perfect homebuying moment exists, underscoring a more personal approach to timing a purchase.
Among Canadians planning to buy within 2 yr, 45% said now feels right, even as 75% reported economic uncertainty made them more cautious.
The central advice: don't try to time the market perfectly; first decide whether the home fits family needs and your budget supports future goals.
Pre-approval can clarify borrowing power, while monthly mortgage payments, down payment, rates, and other expenses should be weighed together against cash flow.
For buyers and renewing owners, ongoing check-ins and early renewal conversations can widen options, support financial resilience, and help keep a mortgage aligned. -
Choosing a Mortgage After a Rate Hold
After Canada's recent rate hold, policy stayed near low-2% and prime near mid-4%, leaving the fixed-versus-variable decision centered on payment flexibility and term length.
Fixed mortgage pricing moved higher as government bond yields climbed in current weeks, while the central bank flagged inflation risks, sharpening attention on variable-rate exposure.
A quarter-point variable-rate increase adds ~$1.25K in first-year interest for every $500K borrowed, before amortization effects, making payment stress-testing essential for borrowers.
Variable mortgages often carry lower prepayment penalties, helping borrowers who may sell or refinance early, while fixed-payment variable loans can send more payment toward interest.
Both mortgage types face the same stress test: borrowers qualify at contract rate plus roughly two points or a low-5% floor, whichever is higher. -
Things You Should Always Keep If You Want to Sell Your Home Fast
Keep natural wood floors even if scratched, as they can be refinished and add value. Retain landscaping accessories like lights and fountains to show outdoor care. Display family photos for warmth. Preserve original architectural details and shelves for storage. Maintain white walls for brightness. Outdoor furniture and mature trees enhance appeal. Avoid removing non-structural walls; open concept is less favored now.
Continue to full article